I Compared Myself to the “Average American.” The Numbers Were a Trap.
 By IlY · Aug 6, 2026 · 6 min read
I went looking for one honest number to tell me if I was doing okay. What I found instead was a stack of statistics designed, almost every one of them, to make me feel a very specific way. Here's what they actually mean once you stop letting them scare you.
It started with a bad night and a search bar.
I'd had one of those days where money feels heavier than usual. Nothing dramatic, just a slow accumulation of small dread. So I did the thing you're not supposed to do at eleven at night, which is type “average American finances” into Google and start scrolling.
What came back was a wall of numbers. Average savings. Average retirement balance. Average income. Average debt. Average net worth. Every one of them presented as a clean, authoritative fact I could measure myself against, and every one of them, I'd eventually realize, quietly rigged.
I read them the way you read a diagnosis. Am I okay? Am I behind? Is everyone else fine and I'm the one who missed something? And each number seemed to answer, in its own way, yeah, you're behind.
It took me a while, and an annoying amount of reading, to understand that the numbers weren't describing me, or my neighbor, or almost anyone real. They were describing a statistical ghost. And once I saw how the ghost was built, the dread mostly went with it.
Here's what I found, and what each number actually means once you stop letting it scare you.
“The average American has $65,000 in savings”
This was the first one that hit me, because I did not have that, and the number felt like proof of failure. Then I found the median. The typical American household has closer to $8,000 in a savings account. The gap between $65,000 and $8,000 is the whole story, and it's the same story that runs through every single one of these stats.
A handful of very wealthy households sitting at the top drag the average up into a place no normal person lives. The “average” savings account isn't the account of an average person. It's an arithmetic artifact. When you read “the average American has $65,000 saved,” the honest translation is “a small number of rich people have a lot, and it makes the math look like this.”
The typical person has $8,000, is stressed about it, and is quietly assuming everyone else has $65,000. Everyone else is assuming the same thing. We're all comparing ourselves to a ghost none of us actually is.
“The average retirement savings is over $330,000”
Same trick, bigger stakes, because this is the number that makes people feel doomed about getting old. The average retirement balance sounds enormous until you find the median, which is dramatically lower, and then break it down by age, which reveals that most people under 45 have a small fraction of that number. The “average” is once again inflated by a relatively small number of large accounts at the top.
But there's a second, sneakier problem with this one, and almost no article mentions it. These figures usually only count money in retirement accounts. They ignore pensions, they ignore Social Security, they ignore home equity, they ignore any wealth held outside a 401k. So a 60-year-old with a modest IRA balance can look catastrophically behind on paper while actually being fine, because the number that scared them left out most of their actual resources.
The retirement stat isn't just distorted by the rich at the top. It's also measuring the wrong thing. It's a number built to make you nervous, and nervous people buy retirement products.
“The average income is around $80,000”
I make less than that, and for a second that stung too. Median household income is meaningfully lower than the average, for the exact reason you now expect. And even the median hides more than it shows, because income means something completely different depending on where you live. $60,000 is a comfortable life in one town and near-poverty in another. A national income figure is almost useless for judging your own situation, because it averages across a country where the cost of living varies by a factor of three or more.
When someone shows you “the average income,” they're showing you a number that describes no actual place and no actual person's cost of reality. It's a headline, not a measurement.
“The average American has $6,000 in credit card debt”
This one flips the emotional trick, and it's worth noticing how. The savings numbers are inflated to make you feel poor. The debt numbers get quoted to make you feel either reassured (“oh, everyone carries a balance, I'm normal”) or alarmed, depending on what's being sold. And the same mean-vs-median distortion applies, a smaller number of people with enormous balances pull the average up, so the typical person carries less than the scary figure suggests.
But the deeper thing about the debt stats is how they get used to normalize something that shouldn't be normal. “The average person carries a balance” quietly reframes carrying high-interest debt as just a normal part of adult life, rather than the expensive trap it usually is. The statistic becomes permission. If everyone's doing it, why shouldn't you?
That's the one place I'd say don't take comfort in being average. Average, here, is a slow leak most people would be better off not matching.
“The average net worth is nearly a million dollars by middle age”
By the time I got to this one I could see it coming, and it's the most extreme version of the whole pattern.
For the 45 to 54 bracket, the average net worth runs close to a million dollars. The median, the actual typical person, is around a quarter of that. This is the single widest mean-vs-median gap of any personal finance number, because net worth is where billionaires do the most damage to the average. One person with a hundred million dollars, dropped into a survey, quietly lifts the “average” of thousands of ordinary households.
Reading “the average person your age is nearly a millionaire” and comparing it to your own balance is one of the most reliably demoralizing things you can do to yourself, and it's built on a number that describes almost no one.
The thing all of these have in common
Line them up and the pattern is undeniable. Every one of these statistics uses the mean, the average, when the median, the typical, would tell you far more. Every one of them is distorted in the same direction, upward, by concentration of wealth at the top. And almost every one of them is quoted in a context where making you feel behind is useful to somebody, because a person who feels behind is a person shopping for a solution.
That's the part that took me longest to accept. It's not usually a conspiracy. Nobody's in a room deciding to lie to you. It's just that the scarier number performs better. It gets more clicks, sells more products, generates more of that eleven-at-night dread that sends people searching for answers they can buy. So the misleading number survives and the honest one gets left out, not by plot, but by incentive.
What I actually do with these numbers now
Almost nothing, and that turned out to be the right amount. I stopped comparing myself to the average anything, because the average is a ghost and comparing yourself to a ghost is a guaranteed loss. When I do look at a stat, I hunt for the median, because the typical person is a real person and the average person isn't. And mostly I've replaced the whole exercise of measuring myself against strangers with one boring question: is my own number better than it was a year ago?
That's it. Up is good. Flat means look closer. Down means look closer, faster. It responds to what I actually do, which is more than any national average has ever done for me.
The statistics aren't lies, exactly. The math is real. But they're built and quoted in a way that reliably makes ordinary people feel like they're failing at a race the numbers were never honestly measuring. Once you see how the ghost is assembled, it loses most of its power to make you feel small.
I went looking for one honest number to tell me if I was okay. It turned out the numbers were never really about me — they were describing a person who doesn't exist, and I'd spent years quietly comparing myself to him.
Money is a skill. Learn it.
Get the weekly letter and the first chapter of the book — free.
Get it free →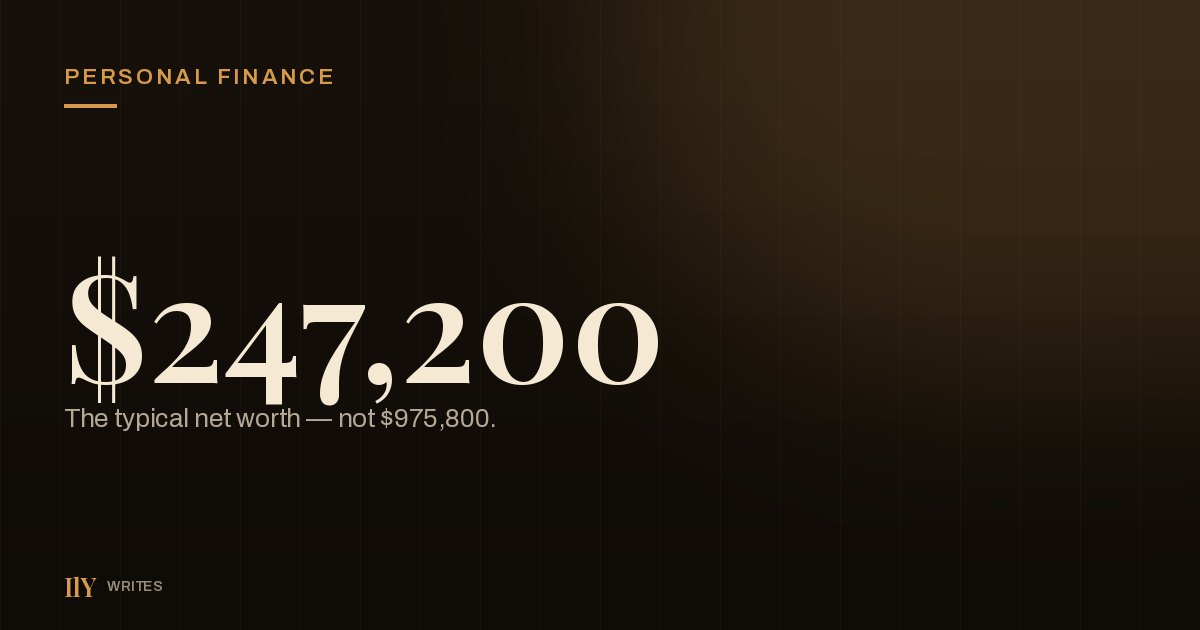
Join the conversation
Comments are powered by Disqus.